
CRWVNBISIRENAMZNGOOGMETA
LLM 2026: From the Illusion of Model Development Stagnation to Large-Scale Real-World Agent Deployment
FUNDA
AWS +15% H200 pricing and rising H100 lease rates signal 2026 compute upcycle; CoreWeave/Nebius/IREN benefit.
By the end of 2025, market anxiety around an “AI bubble” had reached a peak. Model progress seemed to be hitting a wall, capex remained elevated, and skepticism grew louder: could demand realistically justify investment at this scale? Yet as 2026 began, a series of developments has quietly started to invalidate that narrative.
Claude Opus 4.5 launched in November 2025, and—together with the rapid adoption of Claude Code and co-work / agentic workflows—has materially increased compute demand for long-horizon reasoning and collaborative tasks. This shift is already showing up in both pricing and capital-market signals
- After a steady decline beginning in April 2025, H100 leasing price indices have turned upward for the first sustained rebound, while AI infrastructure equities such as CoreWeave, Nebius, and IREN have strengthened in tandem.


- More notably, AWS quietly raised pricing for its machine-learning GPU capacity blocks by roughly 15% in early January 2026. The p5e.48xlarge instance (8× H200) increased from $34.61/hour to $39.80/hour—a move that challenges nearly two decades of consensus that cloud infrastructure pricing trends monotonically downward over time.
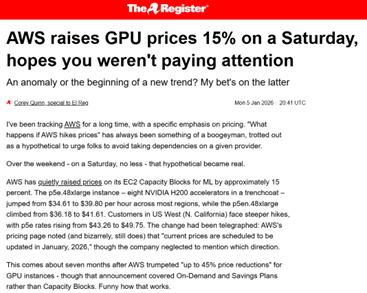
Taken together, these signals point to a deeper conclusion: the market was not witnessing a “bubble bursting,” but rather a transition from a model-centric speculative phase to an agent-driven phase of real, system-level demand. The AI narrative is not collapsing; it is being repriced around longer inference time horizons, higher usage intensity, and more structurally persistent infrastructure demand.
Continue reading with FUNDA
This report is available to subscribers. Sign in or subscribe to read the full analysis.