
ASMLTSMINTCSSNLFQCOMGOOGAVGOTSLAAMD
ASML: Upside from TSMC Expansion, China Demand Resilience, and Intel/Samsung Recovery
FUNDA
TSMC ups Low-NA EUV to 27–28 units, China rev +20% in 2026, and Samsung yield gains lift ASML 2027 EPS.
Over the past fortnight, the market has consistently revised TSMC’s year-end 2026 3nm capacity estimates upward—from an initial 140k wpm to 160kwpm, and subsequently to 180kwpm—reflecting robust demand for GPGPUs and AI ASICs. Beyond 3nm, 2nm tape-out volume is tracking at 1.5x that of 3nm during the comparable period, underscoring rising customer engagement. Driven by strong demand for AI silicon, larger die sizes, and the migration of HBM base dies to foundry processes, AI applications are rapidly consuming front-end foundry capacity. Current supply chain checks indicate that, underpinned by robust advanced node demand, TSMC’s 2026 Low-NA EUV requirements have been revised upward from 22 units to 27-28 units, with 2027 demand projected at a minimum of 40 units.
Potential Upside in Equipment Demand: Further Expansion of TSMC Fab Plans
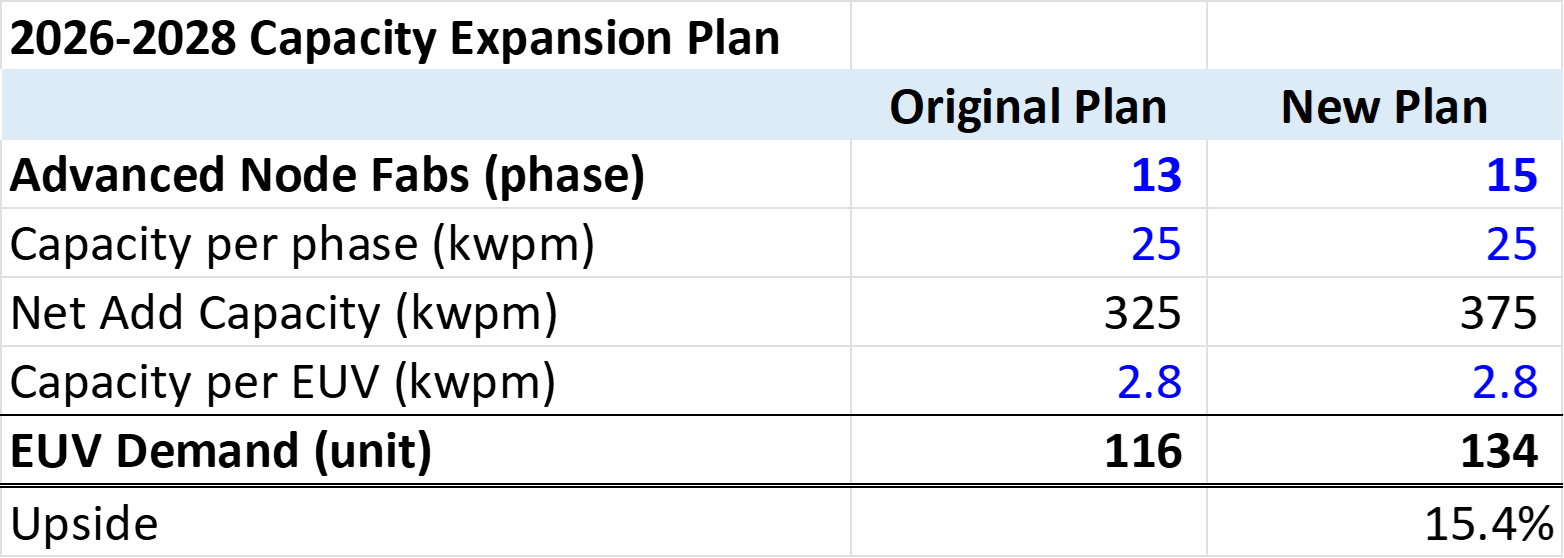
Beyond the aforementioned capacity revisions, equipment suppliers possess further potential upside. Our latest industry checks indicate that TSMC plans to increase its advanced node fab construction over the next three years from the originally planned 13 phases to 15–17 phases. This implies a ~15% potential growth upside for current semiconductor equipment demand.
- Base Scenario (13 Phases): Assuming 25kwpm per phase, the total EUV requirement for 2026-2028 is estimated at 116 units.
- Expansion Scenario (15 Phases): If expanded to 15 phases, total EUV demand lifts 15% to 134 units. This upside, along with the China market demand discussed below, is incorporated into the Bull Case scenario at the end of this report.
China Demand Demonstrates Strong Resilience, Outperforming Pessimistic Market Expectations
Continue reading with FUNDA
This report is available to subscribers. Sign in or subscribe to read the full analysis.