
MU
Review|MU FY26Q4: Visibility Extends to 2028, Supply Tighter Than in 2026
Harvey
Tight memory supply through 2028, rising HBM pricing, and locked-in demand support a longer upcycle for MU.
Micron expects memory supply-demand conditions in CY27 and CY28 to be tighter than in 2026. Customer orders and AI compute demand continue to rise. Even after accounting for planned cleanroom expansions across the industry, Micron sees no clear timeline for supply and demand to return to balance. Management expects prices to keep rising through FY27, though at a more moderate quarter-over-quarter pace. This is consistent with our prior view: memory prices will continue to rise, with the pace constrained by LTAs and customer affordability.
Micron's FY27Q1 gross margin guidance was 75 bps below the buy-side expectations shown below, reflecting additional costs such as incentive compensation and new fab startup expenses. Revenue and EPS results and guidance exceeded those expectations, while FY26Q4 gross margin was in line. Based on our adjustment for the additional costs, gross margin guidance was approximately 80 bps above buy-side expectations. We reiterate our view that this memory cycle will sustain a longer plateau, and we look forward to Micron's planned increase in shareholder returns from December 9, 2026.
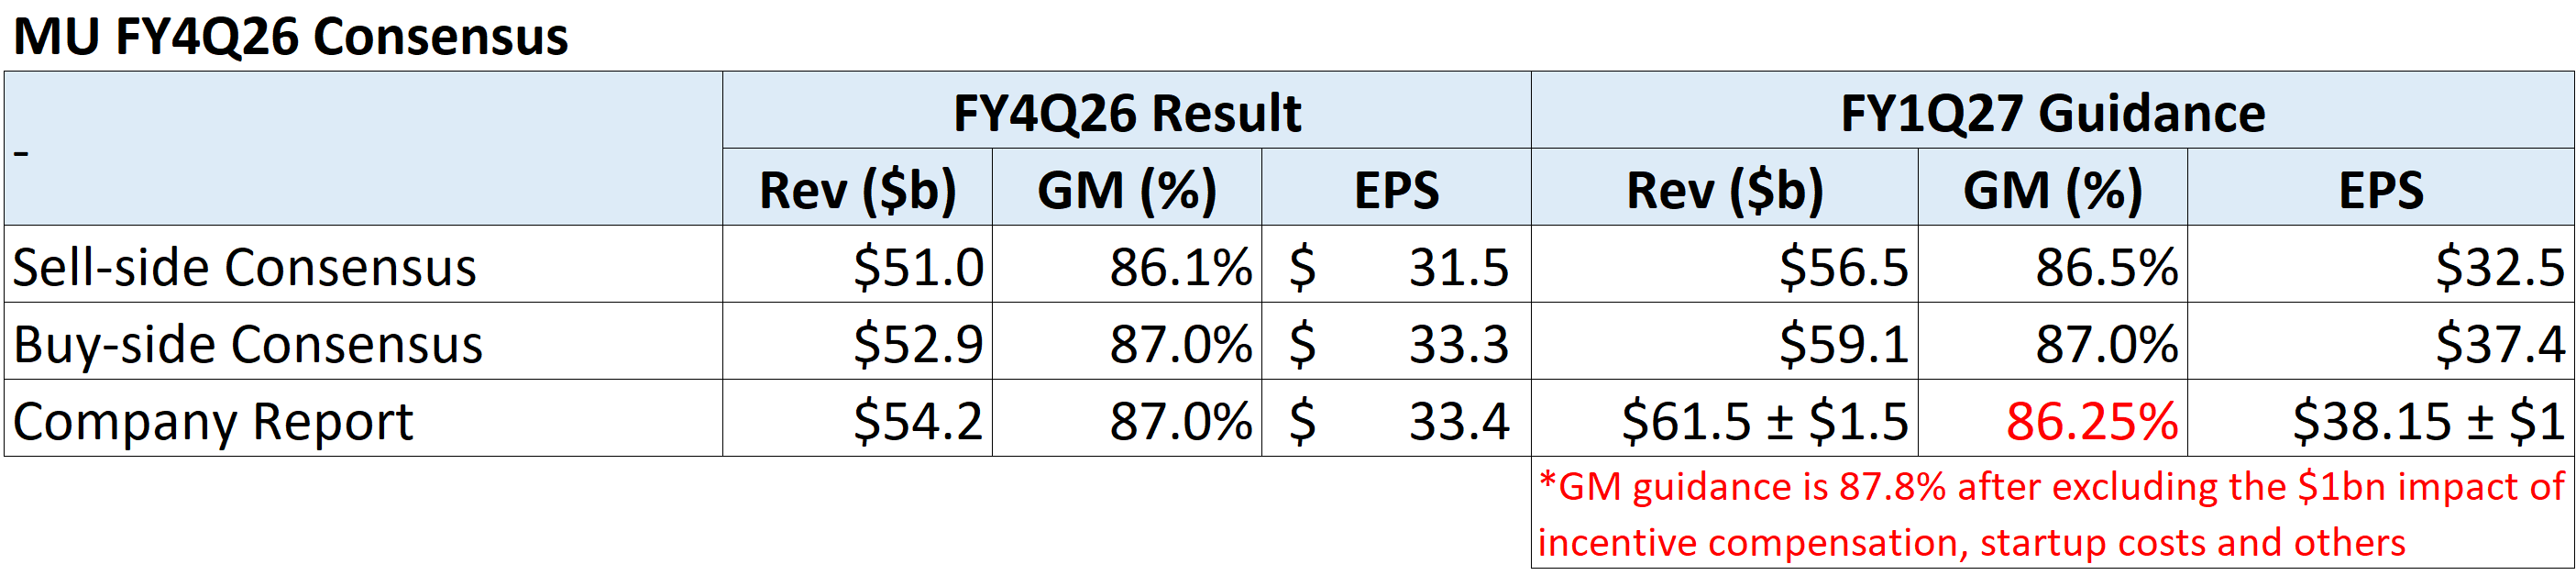
Source: Company, FUNDA estimates
SCA
Management emphasized that newly negotiated Strategic Customer Agreements (SCAs) with pricing terms use higher pricing baselines and bands that reflect current shortages. We therefore believe market concerns about LTAs holding back pricing are overstated.
Continue reading with FUNDA
This report is available to subscribers. Sign in or subscribe to read the full analysis.